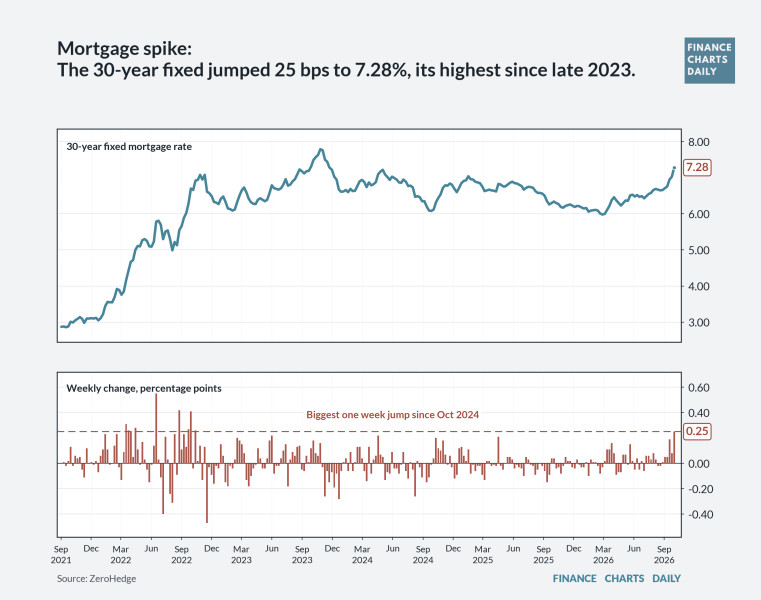
Mortgage rates surge shakes housing market as borrowers face higher costs
Mortgage rates have jumped, driven by inflation and Federal Reserve policy, prompting homeowners and buyers to reassess refinancing and home‑ownership plans.
Key points
- 30‑year fixed mortgage rates have risen sharply this month, linked to inflation and Fed policy changes.
- Higher borrowing costs affect first‑time buyers and those considering refinancing, according to mortgage broker Mr. Thompson.
- Experts advise comparing lenders and weighing closing costs before refinancing in the current rate environment.
The bustling lobby of a major bank in downtown Manhattan is abuzz with conversations about mortgage rates. Homeowners and potential buyers huddle around tables, clutching printouts and laptops, their expressions a mix of anxiety and determination. The air is thick with whispers of rate changes and financial strategies. A recent surge in mortgage rates has stirred the market, leaving many wondering what the future holds for their investments and homeownership dreams.
Current Mortgage Rates: A Sudden Spike
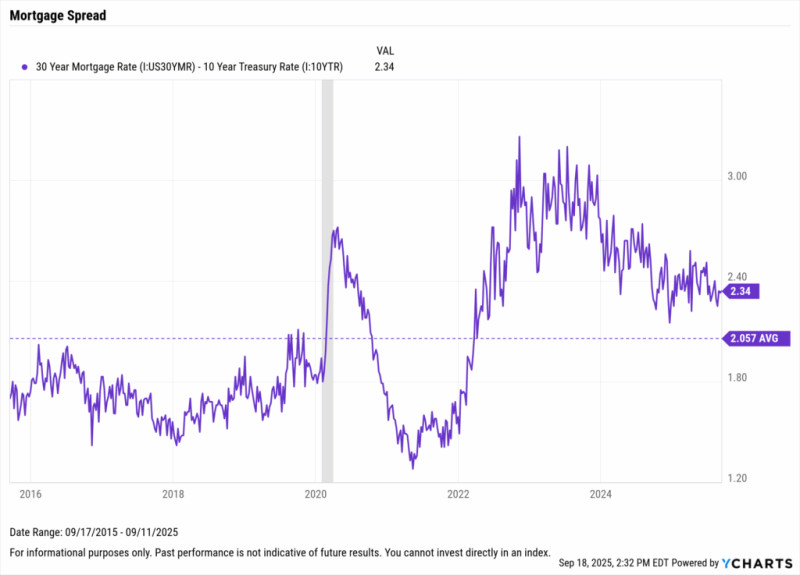
In recent times, the housing market has been jolted by a significant uptick in mortgage rates. As of this month, the average rate for a 30-year fixed mortgage has seen a notable increase, driven by factors including inflationary pressures and changes in monetary policy.
According to available reports, the Federal Reserve's recent policy adjustments have played a pivotal role in this shift. The central bank's actions, aimed at stabilizing the economy, have led to higher borrowing costs for homeowners and buyers alike.
In the bustling office of a prominent financial advisor in New York, Mr. Thompson, a seasoned mortgage broker, explains the situation to a client. "The recent rate hike means that the cost of borrowing has gone up," he says, his voice steady and reassuring. "This affects everyone from first-time homebuyers to those looking to refinance their existing mortgages."
Refinancing in a Changing Market
For many homeowners, refinancing has become a pressing concern. With mortgage rates on the rise, the allure of locking in a lower rate has diminished, leaving many to wonder if refinancing still makes financial sense.
A recent report from LendingTree highlighted the complexities involved in deciding when to refinance.
"Refinancing your mortgage means you pay off and replace your old home loan with a new mortgage. You'll still typically have to pay closing costs — but refinancing may make sense if you want a lower interest rate, new loan term or to cash out equity."
As mortgage rates continue to climb, the decision to refinance becomes increasingly nuanced. Homeowners must weigh the benefits of a lower monthly payment against the costs associated with refinancing.
The situation is further complicated by the varied offerings from different lenders. Bankrate, a leading financial services company, noted that comparing rates from multiple lenders is crucial in this market.
In a recent meeting, Ms. Johnson, a real estate agent, offered her thoughts: "It's a challenging time, but it's also an opportunity. Those who refinance now might secure better terms in the long run."
The Future of Homeownership
As the market adjusts to the new mortgage rates, the long-term implications for homeownership remain uncertain.
Experts like Mr. Thompson caution against making hasty decisions. "It's important to stay informed and consider all options," he advises. "The market is volatile, but with the right strategy, homeowners can navigate these changes successfully."
The surge in mortgage rates has sparked intense discussions about the future of homeownership.
In the quiet corner of a local coffee shop, a group of first-time homebuyers discuss their options. One of them, Sarah, looks thoughtful as she sips her coffee. "We've been saving for years, and now the rates are going up. It feels like we're running out of time," she says, her voice tinged with uncertainty. "But we can't just give up on our dream of owning a home."
In the end, the future of homeownership will depend on how well individuals and families adapt to the changing landscape of mortgage rates. As the market continues to evolve, one thing is clear: the path to homeownership is becoming more complex, and those who navigate it successfully will be rewarded with stability and security in an uncertain world.
Your questions, answered
Why have mortgage rates increased recently?
Rates rose due to inflationary pressures and recent Federal Reserve policy adjustments aimed at stabilizing the economy.
What should homeowners consider before refinancing now?
They should compare multiple lenders, evaluate closing costs, and decide if a lower rate or different loan terms justify the expense.
Quick poll
Should homeowners refinance now despite higher mortgage rates?
0 votes
How does this story make you feel?
Topics
 Up next · BusinessBank of America hit with $1.2 billion anti‑money‑laundering fine